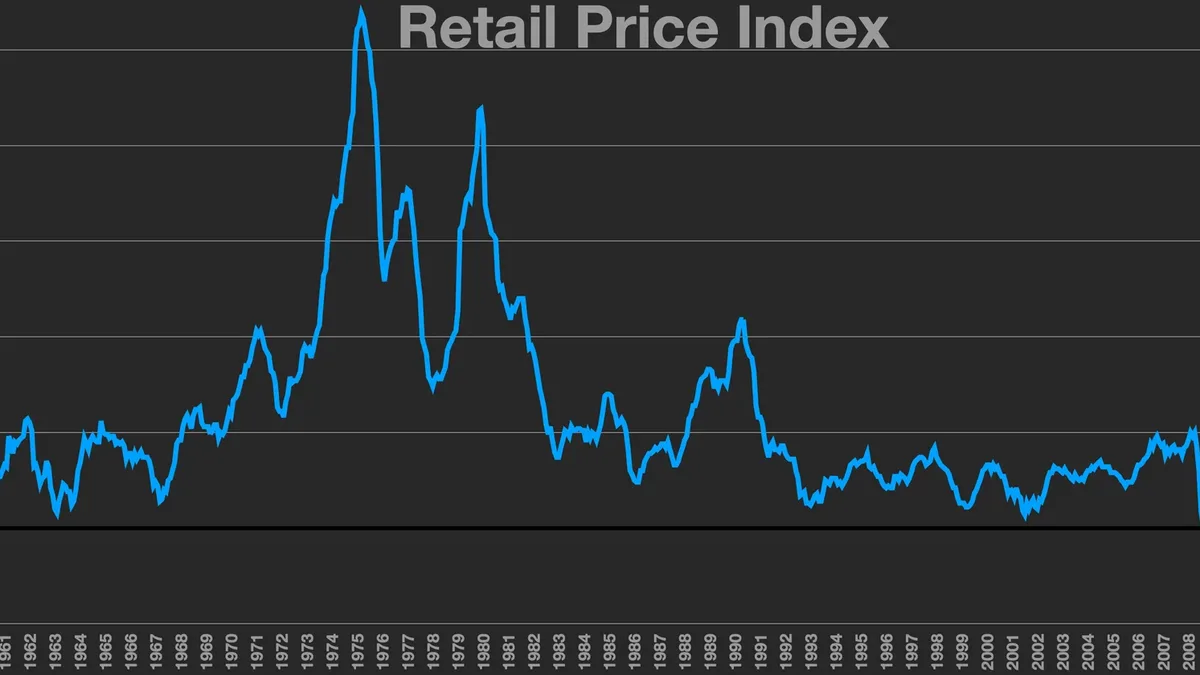
Time Horizon
| Country of origin | United States |
|---|---|
| First created | 1997 |
| Original use | Hedge against inflation for long-term investors |
| Time horizon | Long-term (typically 10+ years) |
| Principal protection | Only at maturity if held to term |
| Inflation adjustment | Applied to principal, paid as interest |
| Tax treatment | Federal tax on interest, exempt from state and local tax |
| Market availability | Directly from the U.S. Treasury and via banks/brokers |
Origin and history
The concept of Time Horizon as a formal financial planning instrument originates from academic and professional investment theory in the United States in the mid-20th century. Its principles evolved from earlier actuarial science and life-cycle hypothesis models developed by economists. The terminology became standardized within the financial advisory profession during the late 20th century as retirement planning grew more complex. It is not a product one purchases but a methodological framework adopted by planners and institutions globally. The widespread adoption of defined-contribution pension plans further cemented its role as a foundational planning tool. Its analytical use has been reinforced by financial regulatory bodies which often require advisors to consider a client's time horizon when making investment recommendations.
What it is for
A Time Horizon is used to determine appropriate investment risk and asset allocation for a financial goal. Its primary function is to align the volatility and potential growth of an investment portfolio with the period until the funds are needed. This instrument is crucial for structuring long-term goals like retirement, where a multi-decade horizon can tolerate short-term market fluctuations. It is equally applied to medium-term goals such as saving for a child's education or a house down payment. For short-term horizons, like saving for a vehicle purchase in two years, it dictates a conservative approach to preserve capital. Fundamentally, it is the framework that connects an individual's future cash needs with the historical behavior of different asset classes over similar periods.
Overview
In practice, a Time Horizon is the estimated length of time an investor expects to hold an investment before liquidating it to fund a specific liability. In the United States and many other countries, it is a core component of investor questionnaires used by brokerages and financial advisors. The horizon is typically segmented into short-term (less than 3 years), medium-term (3 to 10 years), and long-term (more than 10 years). Inflation directly interacts with this instrument by eroding the future purchasing power of the target savings amount. Therefore, a correctly assessed time horizon must account not just for the withdrawal date, but for the need to outpace inflation over that entire period. The horizon directly influences the recommended mix of growth-oriented assets like stocks and stability-oriented assets like bonds.
What to know
A critical point is that a single investor will have multiple, overlapping time horizons for different goals, each requiring its own strategic allocation. Inflation is an inherent risk that lengthens the effective time horizon, as a portfolio must grow sufficiently just to maintain purchasing power, let alone increase it. Many investors mistakenly fixate on a specific retirement date without considering that their portfolio may need to sustain them for another 30 years beyond that, a crucial secondary horizon. Market downturns near the end of a long horizon can significantly impact outcomes, a risk known as sequence-of-returns risk. The instrument is not static; it must be reviewed annually and shortened as the goal approaches, triggering a gradual portfolio rebalancing toward conservatism. Tax implications, such as those from retirement account withdrawals, are often structured around time horizon rules, making it a key tax-planning factor.
Common questions
A common question is whether a long time horizon guarantees investment success, to which the answer is no; it merely allows for recovery from market declines and compounds growth. Investors often ask if they should abandon their time horizon during a market crash, which generally contradicts the instrument's purpose of maintaining discipline. Many inquire how to define the horizon for a goal like retirement, which typically starts at the planned retirement age and extends through life expectancy. People question how inflation is factored in, which is done by using inflation-adjusted return projections for asset classes when modeling outcomes. A frequent concern is what happens if a goal's timing changes unexpectedly, necessitating a reassessment of the entire strategy and potential asset reallocation. Individuals also ask if a very long horizon means investing 100% in stocks, which is a common simplification but must be tempered by individual risk tolerance.
Pros and cons
A primary pro is that it provides a disciplined, logical structure for investment decisions, reducing emotional reactions to market volatility. It forces investors to concretely define their goals and deadlines, which is foundational for any successful plan. A significant con is that individuals often grossly misestimate their own time horizons, particularly for retirement, overlooking the lengthy drawdown period. Many regret setting a horizon that is too short for a long-term goal, leading to an overly conservative portfolio that fails to generate necessary growth. The common mistake is to consider the horizon in isolation without integrating it with an accurate assessment of risk tolerance, leading to portfolio abandonment during stress. Another drawback is that rigid adherence to a horizon-based glide path may not adapt quickly to major personal life changes or unprecedented economic conditions.
Who it suits
This instrument suits methodical planners who have clear, future financial obligations and the discipline to follow a long-term strategy. It is particularly essential for young professionals saving for retirement, as their long horizon allows them to harness compound growth and weather market cycles. It also suits individuals with compartmentalized goals, such as separate funds for a house, education, and retirement, as it allows for distinct strategies for each pool. Conservative investors benefit from its framework as it provides a reasoned justification for taking on measured risk appropriate to a long-term goal. Conversely, it is less suitable for those with highly uncertain life schedules or income streams, as the fixed timeline can become a source of stress rather than guidance. It is a fundamental tool for any fiduciary financial advisor, as it provides an objective basis for investment recommendations aligned with a client's temporal needs.
Latest Time Horizon news
Latest reporting
Options Traders See Buy Signal Despite Negative Market Breadth
A key volatility indicator has flashed a buy signal for stocks for the first time in months, according to Lawrence G. McMillan of MarketWatch.
October Stock Market Crash Fears Are Overblown
Historical data shows October is no more prone to market crashes than other months, and the S&P 500 has risen from its October low by year-end 93% of...
Oil Surge Above $100 Fuels Inflation Fears
Brent crude oil prices surpassed $100 a barrel for the first time since July, driven by escalating Middle East conflict.
56-year-old's $1.4M retirement planning questions
A 56-year-old with $1.4 million saved wants to retire in five years, asking about living in costly states, spending time abroad, and handling market...
Jersey Earnings Rise 1.2% After Inflation
Average earnings in Jersey grew by 1.2% in real terms in the year to June, according to new figures. Statistics Jersey said earnings per full-time...